Beyond the risk score: understanding physical climate risk
Physical climate risk is no longer something real estate investors can consider only through a sustainability or reporting lens. As the effects of storms, flooding, wildfires and rising temperatures become increasingly relevant to real estate assets, questions about exposure and resilience are also finding their way into due diligence, financing and investment decisions.
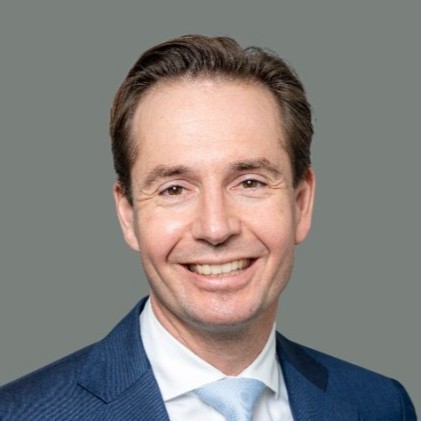
For Martijn Vlasveld, Managing Director, Portfolio Manager and Head of Sustainability Europe at Edmond de Rothschild REIM and a member of the INREV Sustainability Committee, the direction is clear: understanding physical climate risk is becoming part of understanding the investment itself.
It is also why transparency matters. The second paper in INREV’s physical climate risk series focuses on data flows and transparency, mapping how information moves between stakeholders and identifying what is needed to support more consistent physical climate risk assessments.
Different scores, but not necessarily different conclusions
One of the challenges for investment managers is that there is still no single, uniform view of climate risk. The same property can receive different scores from different providers.
Martijn compares this with weather forecasting. ‘I sometimes compare it with weather models giving a slightly different outcome,’ he explains. Climate risk models are developing rapidly, with some providers more advanced in modelling particular hazards than others. ‘This is creating some differences, but the shared direction is generally the same.’
That makes understanding what sits behind a headline risk score just as important as the score itself. Assumptions around climate scenarios, time horizons and hazard definitions can all contribute to different assessment outcomes, reinforcing the importance of transparency around inputs, methodologies and outputs.
A high-risk score is not the end of the story
Another important distinction is between gross and net physical climate risk. Gross risk reflects the location risk before adaptation measures are considered, while net risk reflects what remains after measures that reduce that risk have been considered.
Martijn sees a clear example in the Netherlands: ‘As a large part of the country is below sea level, the gross location risk might be high if the sea flood protection measures are not considered. With these measures, the net location risk is acceptable.’
The same principle applies at asset level. A building may have high gross exposure to storms, but considerably lower vulnerability if it has been constructed with storm protection in mind.
For investment managers, this means moving beyond location-level screening and understanding the characteristics of the building itself. Building specifications such as sunshades or air conditioning can affect an assessment of vulnerability to heat stress, for example. Martijn points to the importance of having detailed building information available and, ideally, complementing the data with an on-site assessment by an asset manager or climate expert.
Bringing climate risk into due diligence
Perhaps the most important development is what happens after a risk has been identified.
‘We are certainly seeing that climate risk is integrated more into financial decisions,’ says Martijn. ‘Climate risk scans are increasingly part of Due Diligence (DD) processes and there are several investors who make an adaptation plan during DD and take these costs into account in the DD findings.’
He also sees investors becoming increasingly cautious about areas with high risks of storms, floods and wildfires, with implications for investor demand and ultimately pricing.
And the effects can extend beyond the acquisition decision. Martijn expects the effects of climate change to be seen first in insurance premiums and, potentially, in the availability of insurance in some locations. Banks are also taking climate risks into account more. ‘When the climate risk is high and unmanaged, the banks might finance less or not at all,’ he explains. ‘So, climate risks influence asset liquidity and hence pricing.’
This shifts the conversation from ‘Does this asset have climate risk?’ to a much more useful investment question: ‘What does this risk mean for this asset, and what are we going to do about it?’
Prioritising the response
Not every identified risk calls for the same response. For Martijn, there is a clear progression: ‘The first step is to identify existing climate risks, the second to map the possible improvement actions and then the third step is to execute the improvements.’
When prioritising those actions, he sees responses to relatively frequent acute hazards as particularly important and an area where capital expenditure can be deployed effectively. Larger, less frequent but potentially higher-impact threats such as flooding require a different approach. In these cases, collaboration with government bodies and other property owners can be essential to reducing risk.
Greater consistency in reporting can support these decisions too. Martijn points to the INREV ESG SDDS, which incorporates climate risk and shows whether the assessed risk is low, medium or high, giving investors and banks greater visibility into whether risk has been assessed and the outcome.
From managing risk to creating resilience
Looking ahead, Martijn expects physical climate risk to become an increasingly established consideration when acquiring new assets and managing existing portfolios.
But adaptation does not have to stop at protecting individual buildings. ‘The real estate industry also has an opportunity to improve the living conditions in the cities by reducing the city heat stress with green roofs, less pavements and more trees,’ he says. ‘We can really make a positive impact here with nature-based solutions.’
Physical climate risk assessment, then, is not simply about producing a better risk score. The real value comes from understanding what sits behind that score, translating it into investment decisions and identifying where action can make an asset more resilient.
Interested in learning more? Explore our physical climate risk paper series for practical guidance in assessing physical climate risk at both asset and portfolio level.